Huge Devaluation: Cashback SBI Card Benefits Revised (Effective April 1, 2026)
SBI Card has announced a major devaluation of the Cashback SBI Card effective April 1, 2026, introducing a ₹4,000 total monthly cap and new excluded categories. Here’s the full breakdown.
Huge Devaluation: Cashback SBI Card Benefits Revised (Effective April 1, 2026)
If you hold the immensely popular CASHBACK SBI Card, brace yourself for a major devaluation. SBI Card has officially announced significant revisions to the card's cashback structure, capping limits, and reward exclusions.
Along with other SBI Card changes happening across their portfolio, these new rules will be strictly implemented starting April 1, 2026.
Here is a complete, simplified breakdown of what is changing, how your cashback will be calculated, and what categories are now excluded.
📌 1. New Cashback Capping Limits (The Biggest Change)
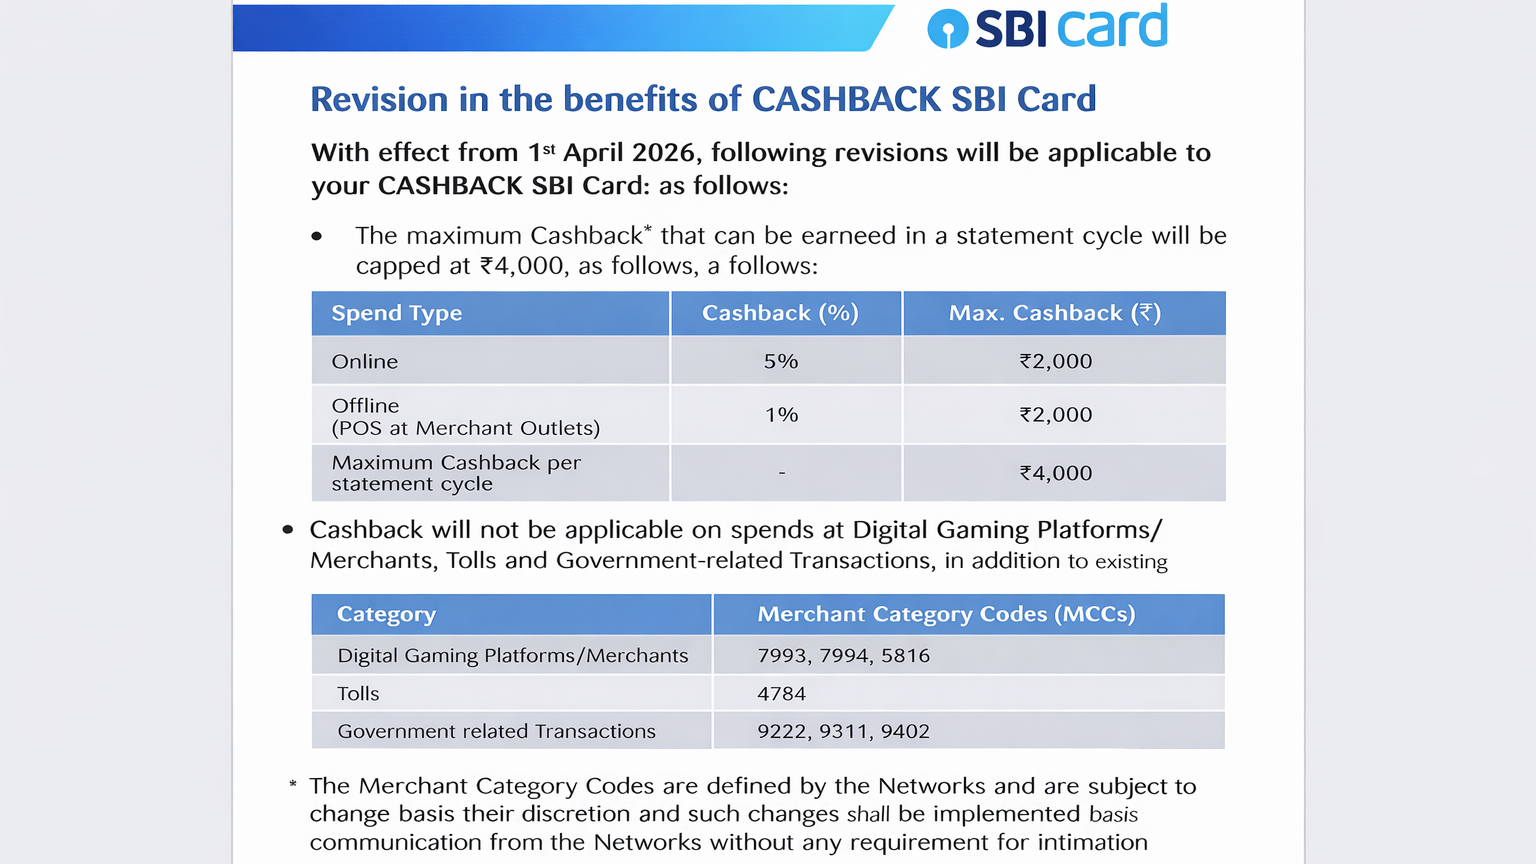
Previously, heavy spenders could maximize their 5% cashback on large online purchases. However, starting April 1, 2026, the maximum cashback you can earn in a single statement cycle is strictly capped at ₹4,000, and it is now divided into specific sub-limits based on your spend type:
- Online Spends (5% Cashback): The maximum cashback you can earn on online transactions is now capped at ₹2,000 per billing cycle. (This means you will max out your 5% reward after spending ₹40,000 online).
- Offline Spends (1% Cashback): For offline POS (Point of Sale) transactions at physical merchant outlets, the cashback is capped at ₹2,000 per billing cycle. (This means you will max out your 1% reward after spending ₹2,00,000 offline).
- Total Monthly Cap: Combining both online and offline categories, the absolute maximum cashback you can earn per statement cycle is ₹4,000.
📌 2. New Excluded Categories (No Cashback)
SBI Card is also expanding its list of restricted categories. Effective April 1, 2026, you will not earn any cashback on the following types of transactions:
- Digital Gaming Platforms/Merchants: (Merchant Category Codes: 7993, 7994, 5816)
- Tolls: (Merchant Category Code: 4784)
- Government-related Transactions: (Merchant Category Codes: 9222, 9311, 9402)
Note: The bank relies on Merchant Category Codes (MCCs) defined by payment networks (like Visa/Mastercard) to identify these spends. If a merchant uses the wrong MCC, your cashback might be affected automatically.
⚠️ Remember the Existing Exclusions!
It is important to remember that these new exclusions are in addition to the already existing restrictions. You still will not earn cashback on:
- Merchant EMI & Flexipay EMI transactions
- Utility bill payments
- Insurance premiums
- Fuel purchases
- Rent payments
- Wallet loads
- School & Educational Services
- Jewelry
- Railways
💡 Final Verdict: Is the CASHBACK SBI Card Still Worth It?
If your primary goal is to use this card for standard online shopping (like Amazon, Flipkart, Myntra, Swiggy, Zomato, etc.) and your monthly online spends are under ₹40,000, this card remains an excellent choice. You will still effortlessly hit that ₹2,000 online cashback cap.
However, if you previously used this card for massive online purchases (like buying expensive electronics or booking high-value flights) expecting unlimited 5% returns, this devaluation will definitely sting.